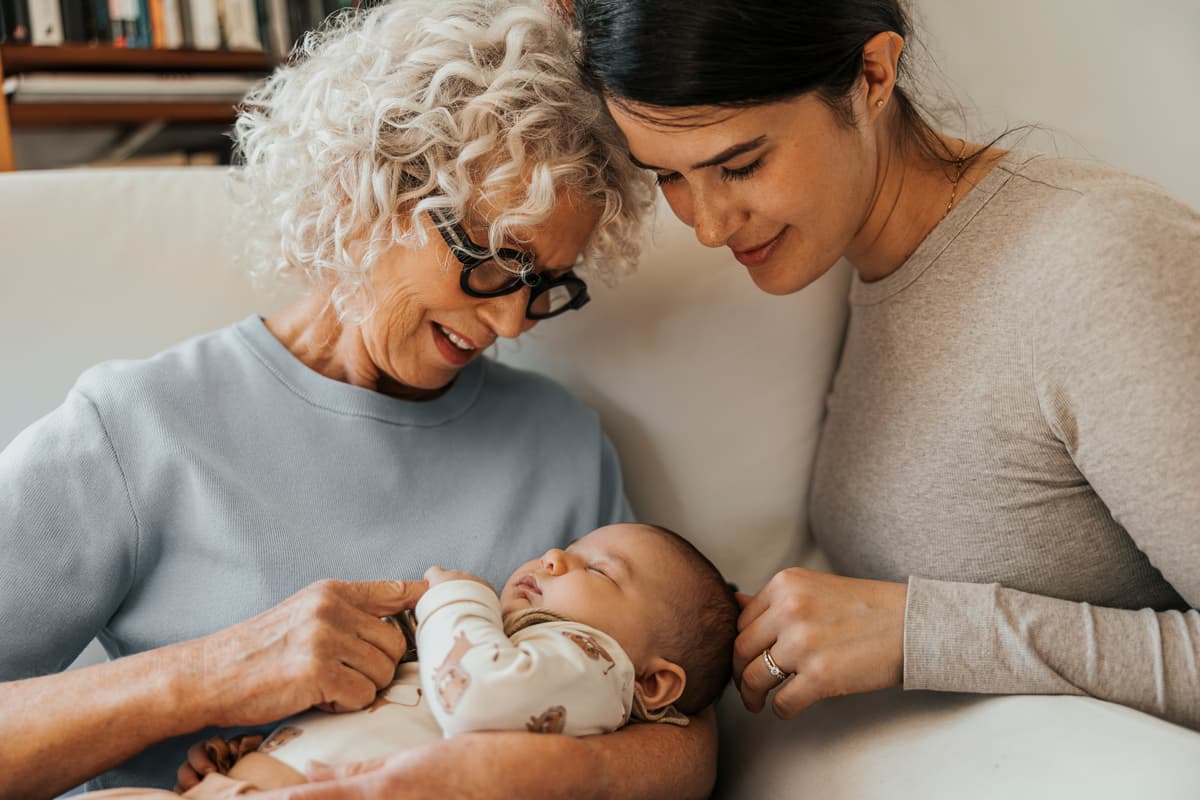
Can I afford to give money to my children now?
Giving money to your children can make a real difference, but it’s important to consider the impact on your own finances too. One of our Personal Wealth Advisers, Lauren Boldy, explains what to think about before deciding how much you can comfortably afford to give.
Allow this video Content?
This content is provided by this video. We need your permission to view it because they may use cookies and other technologies to collect and process your personal data.
AcceptHelping your children financially can be incredibly rewarding. Whether it’s contributing towards a first home, helping with education costs or simply giving them a financial boost, you may feel that your money could make a bigger difference to them now than it would later.
But deciding whether to give money away isn’t always straightforward. Alongside the question of how much you’d like to give is an equally important one: how much can you comfortably afford?
The aim isn’t necessarily to choose between helping your family and protecting your own future. It’s about understanding what you can give without putting your longer-term plans under unnecessary pressure.
Start with your own financial future
It can be tempting to begin with the amount your child needs, particularly when there is an immediate goal such as a house deposit.
But before deciding what to give, it helps to look at your own finances first.
Think about the lifestyle you want in the years ahead and how much it could cost to maintain it. If you’re approaching or already in retirement, that may mean considering your expected income, regular spending and the savings and investments you’ll rely on.
It’s also worth thinking beyond your everyday expenses. You may want to travel, move house or spend more on hobbies and experiences. There could also be unexpected costs later in life.
By looking at the bigger picture, you can start to understand what you may be able to give without compromising the plans you’ve made for yourself.
What if things don’t go to plan?
We can make reasonable assumptions about the future, but we can’t predict everything.
Living costs could rise by more than expected. Investments can fall as well as rise. You may live longer than you planned for, or your health and care needs could change.
That doesn’t mean you shouldn’t give money away. But it does mean it’s worth considering how your finances might cope under different circumstances before making an irreversible decision.
Cash flow modelling can be useful here. It can show how your finances could look over time and explore the impact of different scenarios, including making a significant gift. While it can’t predict what will happen, it can help you understand how different decisions could affect your longer-term plans.
Gifting doesn’t have to mean one large payment
Once you have a better understanding of what you can afford, you can think about how you want to provide support.
A lump sum may make sense if your child needs money for a specific purpose, such as a house deposit. Alternatively, you might prefer to provide smaller amounts over time rather than committing a significant sum at once.
What feels right will depend on your circumstances, your child’s needs and what you want the money to achieve.
There may also be tax and estate-planning considerations. The rules around gifting and inheritance tax can be complex, so it’s important to understand how they could apply to you before making a decision.
Think about the wider family too
Giving money can have implications beyond your finances.
If you have more than one child, you may want to consider whether you intend to treat them equally or simply help each of them when they need it. There’s no single right approach, but thinking about it in advance can make future conversations easier.
It can also be helpful to talk openly about what the gift is for and whether there are any expectations attached to it. A financial gift can be a significant moment for both generations, so making sure everyone understands what has been agreed can help avoid misunderstandings later.
Make gifting part of your financial plan
Wanting to see your children benefit from your money during your lifetime is understandable. And with careful planning, supporting them now doesn’t necessarily have to come at the expense of your own future.
The important thing is to understand what you can afford, consider how different circumstances might affect your plans and take advice before making significant financial decisions.
At Lloyds Wealth, we can help you look at gifting as part of your wider financial plan, considering both the support you want to give your family and the money you may need for the years ahead.
Important information
This article is for information purposes only. It is not intended as investment advice.
Fees, charges and eligibility criteria apply.
Tax treatment depends on individual circumstances and may be subject to change.
Any views expressed are our in-house views as at the time of publishing. This content may not be used, copied, quoted, circulated or otherwise disclosed (in whole or in part) without our prior written consent.
Recommended for you
Pension/inheritance tax changes - your questions answered
Getting ready for the 2027 pension inheritance tax changes with Lloyds Wealth
Preparing for the 2027 pension inheritance tax changes